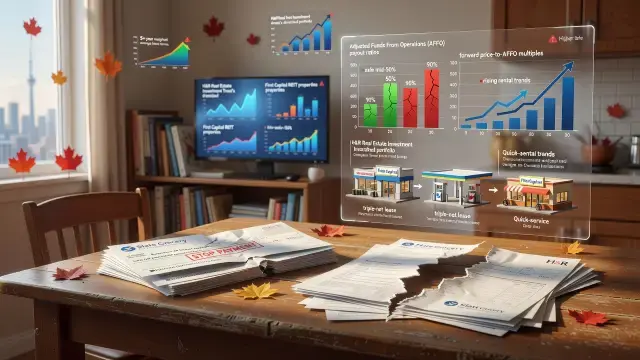
Monthly distribution checks from Slate Grocery Real Estate Investment Trust have stopped arriving, and they are not coming back. The U.S.-focused grocery landlord agreed to a buyout deal on September 28, with closing penciled in for early 2027, and the predictable payout that income investors leaned on has already been pulled from the market. For retirees and conservative savers who built monthly cash flow around commercial real estate trusts, that is not a minor inconvenience. It is a hole in the budget.
Consolidation Is Thinning the Income Shelf
Here's the catch: Slate Grocery is not an isolated case. H&R Real Estate Investment Trust has spent recent years unwinding and reorganizing its portfolio, trimming the asset mix that once made it a diversified income vehicle. First Capital REIT's properties were recently absorbed through acquisition, removing another name from the list of independently traded trusts. Each deal makes sense on its own terms - scale, balance sheet efficiency, strategic focus - but stacked together, they are steadily narrowing the pool of high-yielding, liquid REITs available to everyday Canadian investors. Fewer trusts means less choice, and less choice tends to push income seekers toward higher-risk substitutes if they are not careful.
What Replacement Income Actually Requires
Replacing a lost monthly distribution is not as simple as swapping in the next highest yield on a screener. The thing is, yield alone tells you almost nothing about durability. What matters more is the lease structure behind the cash flow, the payout ratio relative to distributable funds, and how exposed the tenant base is to discretionary spending versus everyday necessities. A trust anchored by grocery stores, gas stations, and quick-service restaurants behaves very differently in a slowdown than one leaning on office space or retail categories tied to consumer discretionary spending.
Net-lease structures matter here too. Under a triple-net arrangement, tenants - not the landlord - absorb property taxes, insurance, and maintenance costs. That shifts inflation risk away from the trust's operating margins and onto operators who are typically better positioned to pass costs through their own pricing. Occupancy rates and weighted average lease terms are the other pieces worth checking; a portfolio near full occupancy with leases running five or more years offers far more visibility into future cash flow than one with shorter-duration tenancies up for renewal in a soft market.
Payout Ratios Separate Durable Income From Fragile Income
The single clearest signal of distribution safety is the Adjusted Funds From Operations payout ratio. A trust distributing in the mid-50% range of its AFFO is retaining meaningful capital - money that can pay down mortgage debt, fund accretive acquisitions, or absorb a rough quarter without touching the distribution. Compare that to trusts paying out 90% or more of AFFO, where there is essentially no cushion if rental income softens or interest costs rise on refinanced debt. For income investors replacing lost monthly cash flow, that payout ratio deserves more attention than the headline yield.
Valuation Still Has to Make Sense
Even a well-structured, conservatively financed trust can be a poor buy at the wrong price. Forward price-to-AFFO multiples let investors compare how much they are paying for a unit of distributable cash flow across different trusts, much the way a price-to-earnings ratio works for equities. A single-digit multiple paired with a rising rental revenue trend and a multi-year history of distribution increases suggests the market may be undervaluing the durability of that income stream - though past growth, it bears repeating, is not a promise of future growth. Consolidation in Canadian commercial real estate is not finished. Investors rebuilding their monthly income streams should expect more deal announcements, not fewer, and should underwrite any replacement holding on fundamentals rather than on yield alone.